Topics
Demand
- Introduction to Microeconomics and Macroeconomics
- Microeconomics
- Macroeconomics
- Macroeconomics Vs Microeconomics
- Introduction to Demand
- Meaning of Demand
- Features of Demand
- Types of Demand
- Determinants of Demand
- Demand Function
- Quantity Demanded and Demand
- Law of Demand
- Demand Schedule
- Demand Curve
- Individual Demand Curve to Market Demand Curve
- Slope of the Demand Curve
- Linear Demand Curve
- Reasons for the Downward Slope of the Demand Curve
- Importance of the Law of Demand
- Exceptions to the Law of Demand
- Movement Along the Demand Curve
- Change in Demand – Shift in Demand Curve
- Difference Between Extension and Increase in Demand
- Difference Between Contraction and Decrease in Demand
- Cross Price Effects
- Relationship Between Income and Demand
- Impact of Tastes and Preferences on Demand for a Commodity
- Industry Demand Vs Firm Demand
- Concept of Utility
- Cardinal Utility Analysis / Marginal Utility Analysis
- Types of Marginal Utility
- Total Utility and Marginal Utility
- Forms of Utility
- Features of Utility
- Relationship Between Total Utility and Marginal Utility
- Law of Diminishing Marginal Utility
- Exceptions of the Law of Diminishing Marginal Utility
- Importance of the Law of Diminishing Marginal Utility
- Consumer's Equilibrium through Cardinal Utility Approach
- Law of Equi-Marginal Utility
- Exceptions of the Law of Equi-marginal Utility
- Importance of the Law of Equi-marginal Utility
- Ordinal Utility Analysis/Indifference Curve Analysis
- Indifference Schedule
- Indifference Curve
- Indifference Map
- Marginal Rate of Substitution (MRS)
- Assumptions of Indifference Curve Analysis
- Properties of Indifference Curves
- Price Line or Budget Line
- Consumer's Equilibrium through Indifference Curve Approach
- Comparison of Utility Theory and Indifference Curve Theory
- Consumer's Equilibrium through Indifference Curve Approach
- Relationship Between Marginal Rate of Substitution and Marginal Utility
Microeconomic Theory
Theory of Income and Employment
- Introduction to Theory of Income and Employment
- Basic Model of Income Determination
- Aggregate Demand and Its Components
- Desired (Ex Ante) and Effective Demand (Ex Post)
- Propensity to Consume or Consumption Function
- Propensity to Save - Saving Function
- Relationship Between Consumption and Saving Functions
- Derivation of Saving Function
- Investment Expenditure
- Private and Public Investment
- Induced and Autonomous Investment
- Determination of Equilibrium Income and Output
- Concept of Aggregate Demand and Aggregate Supply
- Saving-investment Approach
- Investment Multiplier
- Investment Multiplier Defined
- The Multiplier Mechanism
- Graphic Presentation of Multiplier
- Derivation of Multiplier Formula
- Solved Numerical Problems on Propensity to Consume and Save, Equilibrium Income and Multiplier
- Meaning of Full Employment and Voluntary Unemployment
- The Concept of Full Employment
- Voluntary and Involuntary Unemployment
- Excess Demand
- Measures to Correct the Excess Demand
- Deficient Demand
- Measures to Correct Deficient Demand
- Deficient and Excess Demand and Business Cycle
- Aggregate Demand in a Three - Sector Economy
- Features of the Consumption Function
- Shifting of the Consumption Function
- Importance of the Consumption Function
- Gross Investment and Net Investment
- Paradox of Thrift
- Variables
- Partial and General Equilibrium
- Static Analysis
- Comparative Static Analysis
- Dynamic Analysis
- Difference between Static and Dynamic Analysis
- Psychological Law of Propensity to Consume
- Measures to Raise Propensity to Consume
- Importance of Investment
- Static Multiplier
- Dynamic Concept of Multiplier
- Limitations of Multiplier
- Leakages of Multipler
- Importance of Multiplier
- Types of Multiplier
- Balanced-Budget Multiplier
- Unemployment Associated with Full Employment
- Inflationary Gap
- Foreign Trade Policy
Elasticity of Demand
- Introduction to Elasticity of Demand
- Meaning and Types of Elasticity of Demand
- Price Elasticity of Demand
- Classification of Price Elasticity - Degrees of Price Elasticity of Demand
- Methods of Measuring Price Elasticity of Demand
- Percentage or Proportionate Method
- Total Expenditure Method
- Point Method (Geometric Method)
- Arc Elasticity of Demand
- Revenue Method
- Numerical Problems of Price Elasticity of Demand
- Factors Affecting Price Elasticity of Demand
- Importance of Elasticity of Demand
- Income Elasticity of Demand
- Types of Income Elasticity of Demand
- Importance of Income Elasticity
- Cross Elasticity of Demand
- Туpes of Cross Elasticity of Demand
- Limitations of Cross Elasticity of Demand
- Importance of Cross Elasticity of Demand
Money and Banking
Supply
- Concept of Supply
- Individual and Market Supply
- Distinction Between Supply and Stock
- Determinants of Supply
- Supply Function
- Law of Supply
- Supply Schedule
- Supply Curve
- Derivation of Market Supply Curve From Individual Supply Curves
- Explanation of the Law of Supply
- Time Period and Supply
- Exceptions to the Law of Supply
- Movement Along the Supply Curve Or Expansion and Contraction of Supply
- Shift of the Supply Curve or Change in Supply
- Expansion of Supply and Increase in Supply
- Contraction of Supply and Decrease in Supply
- Elasticity of Supply
- Meaning and Types of Elasticity of Demand
- Price Elasticity of Supply
- Categories (Degrees) of Elasticity of Supply
- Measurement of Elasticity of Supply > Percentage Method
- Measurement of Elasticity of Supply > Geometric or Point Method
- Determinants of Elasticity of Supply
- Importance of Elasticity of Supply
Market Mechanism
- Introduction to Market Mechanism
- Basic Concepts of Equilibrium and Equilibrium Price
- Equilibrium Price and Quantity in a Competitive Market
- Changes in Equilibrium
- Effects of Changes (Shifts) in Demand on Equilibrium Price and Equilibrium Quantity
- Effects of Changes (Shifts) in Supply on Equilibrium Price and Equilibrium Quantity
- Effects of Simultaneous Changes (Shifts) in Demand and Supply
- Some Special Cases of Equilibrium
- Importance of the Element in the Determination of Price
- Applications of Tools of Demand and Supply Price Control
- Mаximum Price Legislation or Price Ceiling and Rationing
- Minimum Price Legislation or Floor Price
- Important Areas of Applications of Tools of Demand and Supply Curves
- Meaning of Perfect Competition
- Assumptions and Conditions of Perfect Competition
- Pure and Perfect Competition
- Time Element in the Theory of Price Determination
- Determination of Equilibrium Prices
- Normal Price and Law of Returns
- Comparison between Market Price and Normal Price
- Practical Applications of Tools of Demand and Supply Analysis
Balance of Payments and Exchange Rate
Public Finance
Concepts of Production
- Concept of Production
- Product
- Factors of Production
- Production Function
- Short-run and Long-run
- Features of Production Function
- Types of Production Functions
- Some Basic Concepts - Total, Average and Marginal Physical Products
- Relationship between Average Product (AP) and Marginal Product (MP)
- Relationship between Total Product (TP) and Marginal Product (MP)
- Returns to a Factor - Laws of Returns to a Variable Factor
- Law of Variable Proportions
- Statement of the Law of Variable Proportions
- Assumptions of the Law of Variable Proportions
- Illustration of the Law of Variable Proportions
- Three Stages of Production
- Explanation of the Law of Variable Proportions
- Stages of Operation and the Decision to Produce
- Conditions Or Causes of Applicability
- Applicability of the Law of Variable Proportions
- Changes in Production
- Returns to a Factor or Law of Returns
- Law of Variable Proportions and Returns to Scale Compared
- Variation of Output in the Long Run - Returns to Scale
- Scale of Production
- Concept of Indivisibility
- Economies of Scale
- Diseconomies of Scale
National Income
Cost and Revenue
- Introduction to Cost of Production
- Money Cost Or Accounting Cost / Explicit Cost
- Economic Cost
- Opportunity Cost
- Real Cost
- Private and Social Cost
- Fixed Cost and Variable Cost
- Different Cost Concepts
- Total Cost Curves
- Average Cost Curves
- Marginal Cost (MC)
- Relationship between Average and Marginal Cost
- Long-Run Cost Curves
- Long-run Average Cost (LAC) Curve
- Long-run Marginal Cost (LMC) Curve
- LAC Curve U-shaped - Economies and Diseconomies of Scale
- Numerical Problems Long-run Cost Curves
- Revenue Concepts
- Behaviour of Revenue Under Different Market Structures
- Relationship Between Total, Average and Marginal Revenues Under Perfect Competition
- Relationship Between Total, Average and Marginal Revenue Under Imperfect Competition
- Significance of Revenue Curve
- Numerical Problems of Revenue
Main Market Forms and Equilibrium of a Firm
- Concept of Market
- Market Structure
- Factors Determining Market Forms
- Perfect Competition
- Features of Perfect Competition
- Pure and Perfect Competition
- Monopoly
- Features of Monopoly
- Monopolistic Competition
- Features of Monopolistic Competition
- Oligopoly
- Features of Oligopoly
- Monopsony
- Features of Monopsony
- Duopoly
- Characteristics of Duopoly
- Bilateral Monopoly
- Other Forms of Market
- Factors Determining Market / Extent of Market
- Demand Curves of Firms under Different Market Forms
- Comparison between different forms of market
- Difference Between Imperfect Competition and Monopolistic Competition
- Firm : An Economic Entity
- Profit Maximisation Objective
- The Definition of Profits
- Rules for Profit-Maximisation
- Producer's (Firm's) Equilibrium: Total Revenue and Total Cost Approach
- Producer's (Firm's) Equilibrium: Marginal Revenue and Marginal Cost Approach
- Short-run Equilibrium
- Long-run Equilibrium
- Firm is a Price Taker, Not a Price Maker
- Equilibrium of Industry
- Difference Between Firm and Industry's Equilibrium
- Meaning of a Producer
- Producer's Equilibrium under Perfect Competition
- Determination of Price and Equilibrium Under Monopoly
- Monopoly Equilibrium and Laws of Costs
- Price Discrimination or Discriminating Monopoly
- Price and Output Discrimination Under Discriminating Monopoly
- Measures of Monopoly Power
- Nature of Demand and Cost Curves
- Equilibrium Price and Output under Monopolistic Competition
- Group Equilibrium in Monopolistic Competition
- Product Differentiation
- Selling Costs
- Equilibrium with Selling Costs
- Price and Output Under Oligopoly Indeterminate
- Price and Output Determination under Oligopoly
- Price Rigidity-Sweezy's Kinky Demand Curve Model or Equilibrium under Independent Action
- Reasons for Price Stability
- Cournot's Model
- Collusive Oligopoly
- Mergers
- Introduction
- Definition: Psychological Law of Propensity to Consume
- Assumptions
- Propositions
- Tabular illustration
- Diagrammatic explanation
- Implications
- Key Points: Psychological Law of Propensity to Consume
Introduction
Keynes’ Psychological Law of Propensity to Consume describes how people change their consumption when their income changes. It says that as income increases, people do spend more, but they do not spend the entire additional income on consumption; they also increase their saving.
This law is also called Keynes’ Fundamental Law of Consumption and is a key part of his theory of income and employment.
Definition: Psychological Law of Consumption
“The psychology of the community is such that when aggregate real income is increased, aggregate consumption is also increased, but not by so much as income.” — Keynes
Assumptions
1. Constancy of Psychological–Institutional Complex
Factors like habits, tastes, customs, income distribution, price level, and population do not change in the short run. Consumption depends on income alone.
2. Normal Conditions
The economy is free from abnormal situations such as war, revolution, hyperinflation, or floods. Under such emergencies, people may spend their entire income, breaking the law.
3. Rich Capitalist Economy (Laissez-faire)
The law applies to a free-market capitalist economy with minimum government interference. In a poor economy, almost all income goes to consumption; in a heavily regulated one, government controls can alter saving–spending decisions.
Propositions
Keynes explained his law through three related propositions.
1. When income increases, consumption increases but by a smaller amount
- As income rises, consumption expenditure also rises, but not in the same proportion.
- Once basic needs are largely satisfied, each extra rupee of income is partly used for extra consumption and partly added to saving, so the marginal propensity to consume is less than one.
2. Increased income is divided between consumption and saving
- The increment in income is split into two parts: an increment in consumption (ΔC) and an increment in saving (ΔS).
- Symbolically, this can be written as:
ΔY = ΔC + ΔS - The part that is not spent on consumption automatically appears as saving.
3. Higher income does not reduce total consumption or total saving
- When aggregate income increases, both total consumption and total saving in the economy tend to rise.
- It is highly unlikely that, with a higher income, people will reduce either their overall consumption or their overall saving; at worst, one of them may remain constant in the short run.
Tabular illustration
| Income (₹) | Consumption (₹) | Saving (₹) | Interpretation |
|---|---|---|---|
| 0 | 40 | −40 | Even with zero income, people need minimum consumption for survival; they dissave or borrow. |
| 100 | 100 | 0 | Break‑even level: income equals consumption, and saving is zero. |
| 200 | 150 | 50 | Positive saving begins; consumption rises less than income. |
| 300 | 190 | 110 | Saving increases further as income rises. |
| 400 | 220 | 180 | The gap between income and consumption widens; more of the extra income is saved. |
| 500 | 240 | 260 | At high income, saving becomes a large proportion of income. |
| 600 | 250 | 350 | Consumption is almost constant while saving rises sharply. |
This schedule shows that as income increases, both consumption and saving increase, but the share of income going to saving becomes larger over time.
Diagrammatic explanation
- The 45° line from the origin represents all points where income equals consumption (Y = C), so saving is zero on this line.
- The upward‑sloping line C is the consumption function. At low income level Y0, consumption E0Y0 is greater than income; the vertical segment E0P1 shows dissaving, equal to S0Y0 on the saving curve.
- At income level Y, point E lies on both the 45° line and the C curve; here income equals consumption and saving is zero. This is the break‑even point.
- At higher income level Y1, consumption E1Y1 is less than income Y1P2; the vertical gap between the 45° line and the C curve (shown as E2E1 or S1Y1) represents positive saving.
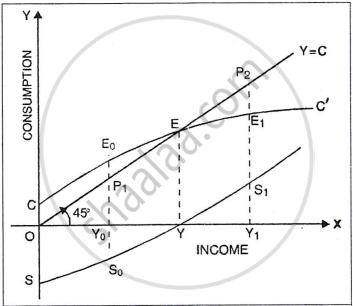
Thus the diagram visually confirms the law: as income rises, consumption rises but the gap between income and consumption (saving) becomes larger.
Implications
1. Critical Importance of Investment
Consumption is stable in the short run, so income and employment can only rise through more investment.
2. Refutation of Say's Law
Say's Law says "supply creates its own demand" (MPC = 1). Since MPC < 1, not all output is consumed → demand can fall short of supply → Say's Law is invalid.
3. Declining Marginal Efficiency of Capital (MEC)
Rich communities save more → aggregate demand falls → prices fall → profits fall → expected return on capital (MEC) declines.
4. Under-Employment Equilibrium
AD = AS can occur below full employment because consumption (and therefore AD) is not large enough to absorb full-employment output.
5. Income-Generation Process (Multiplier)
Because MPC < 1, each spending round is smaller → income rises in diminishing steps → this is the multiplier process.
\[K=\frac{1}{1-MPC}\]
Example: If MPC = 0.8, then K = 5. A ₹100 crore investment creates ₹500 crore of income.
6. Over-Saving Gap
In rich economies, saving grows faster than investment opportunities → excess saving → fall in AD → danger of economic crash.
7. Secular Stagnation
Long-run problem: if growing savings cannot find investment outlets, the economy faces prolonged depression and unemployment.
8. Need for State Intervention
Free markets cannot automatically close the saving–investment gap → government must boost consumption in recession and control it in inflation.
9. Wages and Employment Controversy
Wage cuts reduce income of workers (high MPC) → AD falls → depression worsens. So, unlike classical belief, cutting wages does not increase employment.
10. Unique Nature of Income Propagation
People save part of extra income → each successive spending round is smaller → income propagation is gradual and finite, explained by the multiplier.
11. Turning Points of Business Cycles
During a boom, consumption lags behind rising income → saving gap grows → overproduction → downturn begins before full employment is reached.
Key Points: Psychological Law of Propensity to Consume
- Consumption increases when income increases, but less than income.
- Part of the extra income is saved.
- MPC < 1 (Marginal Propensity to Consume is less than one).
- Formula: ΔY = ΔC + ΔS
- Break-even point: Income = Consumption (Saving = 0).
- Higher income → higher savings.
- Investment and government action may be needed to maintain demand.
