Topics
Commercial Mathematics
Compound Interest
- Compound Interest as a Repeated Simple Interest Computation with a Growing Principal
- Use of Compound Interest in Computing Amount Over a Period of 2 Or 3-years
- Use of Formula
- Finding CI from the Relation CI = A – P
Goods and Services Tax (G.S.T.)
Algebra
Banking
Geometry
Shares and Dividends
Linear Inequations
Mensuration
Quadratic Equations
Trigonometry
Ratio and Proportion
Statistics
Probability
Factorisation of Polynomials
- Function and Polynomial
- Division Algorithm for Polynomials
- Remainder Theorem
- Factor Theorem
- Applications of Factor Theorem
Matrices
Arithmetic and Geometric Progression
Co-ordinate Geometry
- Foundation of Coordinate Geometry
- Advanced Concept of Reflection in Mathematics
- Invariant Points
- Combination of Reflections
- Using Graph Paper for Reflection
Similarity
Symmetry
Loci
- Locus
- Points Equidistant from Two Given Points
- Points Equidistant from Two Intersecting Lines
- Summary of Important Results on Locus
- Important Points on Concurrency in a Triangle
Circles
Tangent and Secant Properties
Constructions
Area and Volume of Solids (Cylinder, Cone and Sphere)
- Mensuration of Cylinder
- Hollow Cylinder
- Mensuration of Cones
- Mensuration of a Sphere
- Hemisphere
- Conversion of Solids
- Solid Figures
- Problems on Mensuration
Trigonometrical Identities
Heights and Distances
- Angles of Elevation and Depression
- Problems based on Elevation and Depression
Statistics : basic concepts, Mean, Median, Mode. Histograms and Ogive
Probability
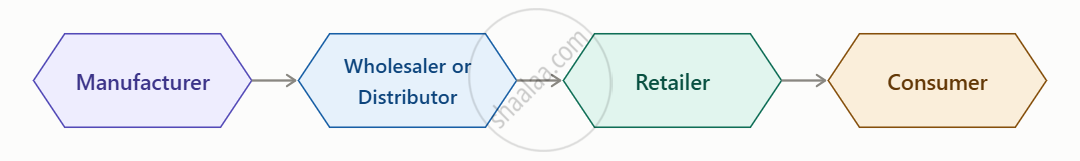
GST Trading Chain
A trading chain shows how goods move from production to the final consumer:
Working of GST in a Supply Chain
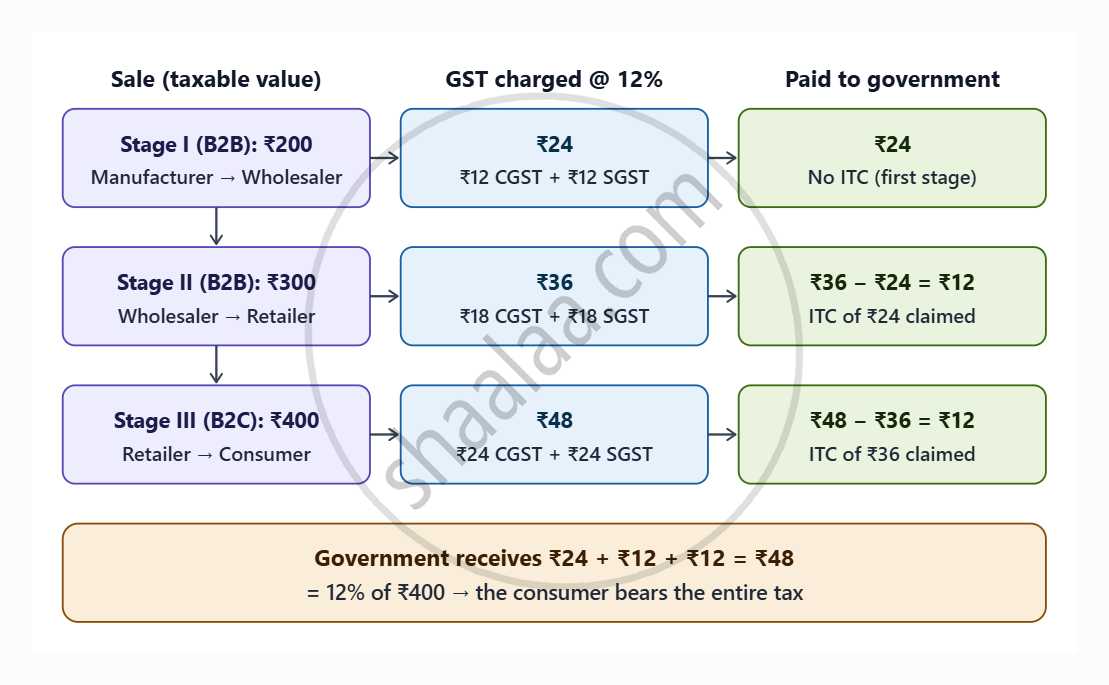
Definition: Input Tax Credit (ITC)
Input Tax Credit (ITC) is the credit a registered dealer can claim for GST paid on purchases used in the course of business.
\[ \boxed{\text{GST Payable} = \text{Output GST} - \text{Input GST (ITC)}} \]
Example
Question: Suppose a manufacturer sold a cycle for a taxable value of ₹ 4000 to the wholesaler. Wholesaler sold it to the retailer for ₹ 4800 (taxable value). Retailer sold it to a customer for ₹ 5200 (taxable value). Rate of GST is 12%. Complete the following activity to find the payable CGST and SGST at each stage of trading.
Solution:
Trading chain
\[ \text{Manufacturer} \xrightarrow{(\text{₹}4000, \; 12\%)} \text{Wholesaler} \xrightarrow{(\text{₹}4800, \; 12\%)} \text{Retailer} \xrightarrow{(\text{₹}5200, \; 12\%)} \text{Customer} \]
Stage 1: Manufacturer
\[ \text{Output tax of manufacturer} = 12\% \text{ of } 4000 = \frac{12}{100} \times 4000 = \text{₹}480 \]
The manufacturer has no input tax, so:
\[ \text{GST payable by manufacturer} = \text{₹}480 \]
Stage 2: Wholesaler
\[ \text{Output tax of wholesaler} = 12\% \text{ of } 4800 = \text{₹}576 \]
\[ \therefore\; \text{GST payable by wholesaler} = \text{Output tax} - \text{Input tax} \]
\[ = 576 - 480 \]
\[ = \text{₹}96 \]
Stage 3: Retailer
\[ \text{Output tax of retailer} = 12\% \text{ of } 5200 = \frac{12}{100} \times 5200 = \text{₹}624 \]
\[ \therefore\; \text{GST payable by retailer} = \text{Output tax of retailer} - \text{ITC of retailer} \]
\[ = 624 - 576 \]
\[ = \text{₹}48 \]
Statement of GST payable at each stage of trading
CGST and SGST are each half of the GST payable ( \[ 6\% + 6\% \] ).
\[ \begin{array}{|l|c|c|c|} \hline \textbf{Individual} & \textbf{GST payable} & \textbf{CGST payable} & \textbf{SGST payable} \\ \hline \text{Manufacturer} & \text{₹}480 & \text{₹}240 & \text{₹}240 \\ \hline \text{Wholesaler} & \text{₹}96 & \text{₹}48 & \text{₹}48 \\ \hline \text{Retailer} & \text{₹}48 & \text{₹}24 & \text{₹}24 \\ \hline \text{Total} & \text{₹}624 & \text{₹}312 & \text{₹}312 \\ \hline \end{array} \]
Check: total GST = \[ \text{₹}624 = 12\% \text{ of } \text{₹}5200, \] which is the tax the customer pays on the final price.
Key Points: GST in Trading Chain
- GST is an indirect tax on the supply of goods and services.
- Intra-state sales attract \[ \text{CGST} + \text{SGST}. \]
- Inter-state sales attract IGST.
- GST is charged at each stage: \[ \text{manufacturer} \rightarrow \text{wholesaler} \rightarrow \text{retailer} \rightarrow \text{consumer}. \]
- Registered dealers claim Input Tax Credit for GST paid on eligible purchases.
- Net GST payable is calculated as: \[ \boxed{\text{GST Payable} = \text{Output GST} - \text{Input GST (ITC)}} \]
- The final consumer pays the total GST included in the final invoice.
- Total GST deposited by all dealers equals the GST paid by the final consumer.
